
Why a Kitchen Renovation Loan Might Be Your Best Move
A kitchen renovation loan is a financing option that allows homeowners to borrow money specifically for upgrading their kitchen, with repayment terms typically ranging from 2-12 years. These loans come in several forms, each with distinct advantages:
Main Kitchen Renovation Loan Types:
- Personal Loans – Unsecured, no collateral needed, $5,000-$100,000, rates from 7.99%-39.9% APR
- Home Equity Loans – Secured by your home, lower rates, lump-sum payment, fixed terms
- Home Equity Line of Credit (HELOC) – Revolving credit line, borrow as needed, variable rates
- Contractor Financing – Often includes promotional 0% APR periods (6-12 months), $1,000-$100,000
The kitchen is often called the heart of the home. It’s where meals are prepared, memories are made, and conversations flow. But what happens when your kitchen no longer reflects your lifestyle or meets your functional needs?
Maybe your countertops are outdated, your appliances are failing, or your layout just doesn’t work for how your family actually lives. The vision of your dream kitchen is clear in your mind. The reality, however, is that a full kitchen renovation can cost $25,000-$50,000 or more, depending on the size and scope of your project.
Here’s the good news: financing makes your dream kitchen attainable without draining your savings or liquidating investments. Whether you’re planning a complete overhaul or targeted upgrades, understanding your loan options helps you move forward with confidence.
The cost of renovation doesn’t have to be a barrier when you have the right financing strategy.
First, Let’s Talk Numbers: Budgeting for Your Dream Kitchen

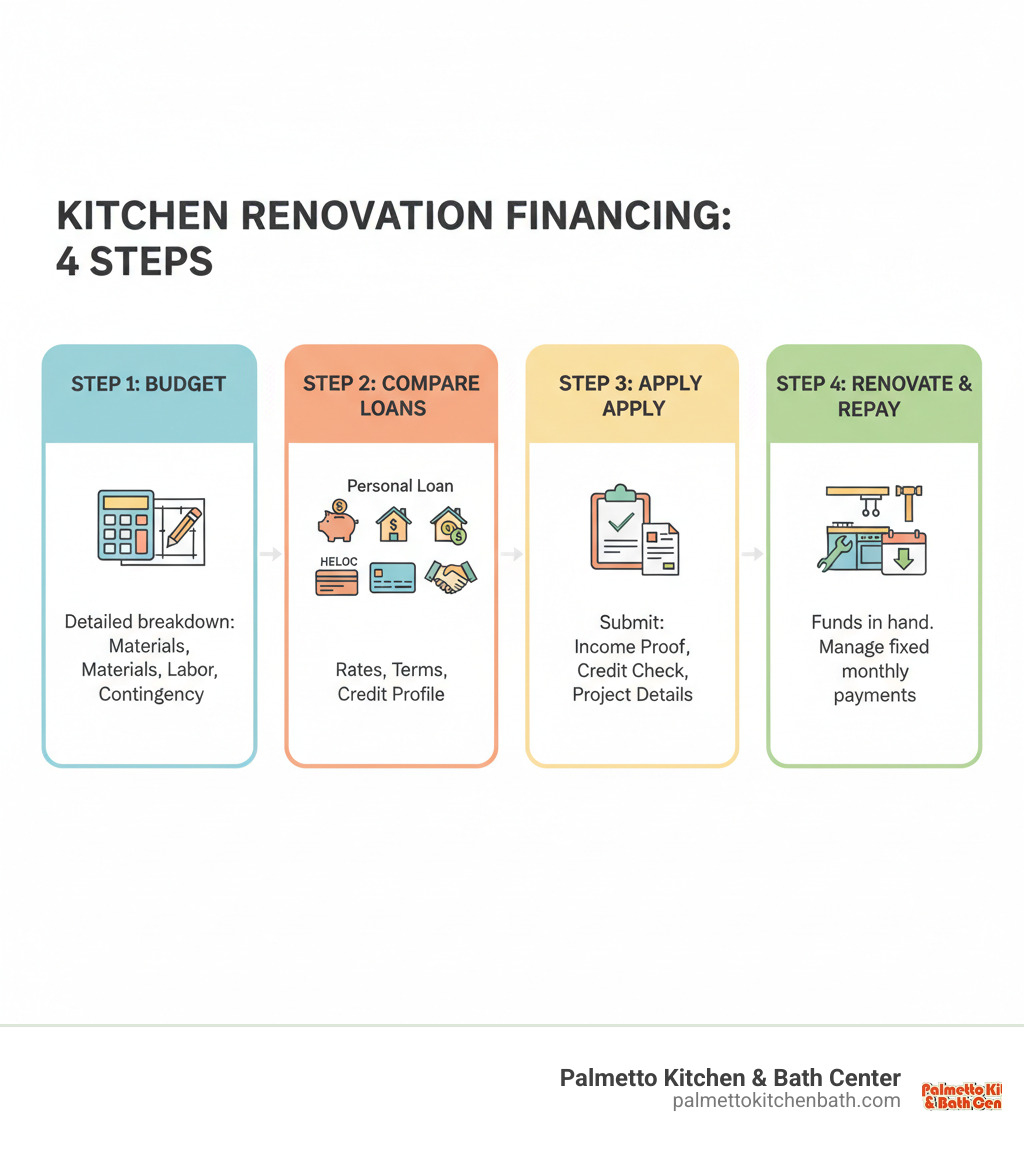
Before you start browsing loan options, let’s talk about the most important step: figuring out what your dream kitchen will actually cost. Trust me, having a solid budget from the start saves you from that sinking feeling of running out of money halfway through your renovation. We’ve seen it happen to homeowners who skipped this step, and it’s heartbreaking.
The truth is, kitchen remodeling costs can vary wildly. Your neighbor’s renovation might have cost $30,000 while your sister’s was $80,000. Why? Because every kitchen is different. The size of your space, how much you’re changing, the materials you choose, and even where you live all play a role.
Here in South Florida, we typically see full kitchen renovations ranging from $25,000 to $50,000 or more. But that’s a pretty wide range, right? Let’s break it down by kitchen size so you have a clearer picture.
A small kitchen (around 70 to 100 square feet) usually falls in the $10,000 to $20,000 range. If you have a mid-size kitchen (100 to 200 square feet), you’re looking at $20,000 to $70,000. And for those lucky enough to have a large kitchen (over 200 square feet), the budget typically lands between $70,000 and $130,000.
Want a more detailed breakdown specific to our area? Check out our guide on Understanding Kitchen Remodeling Costs in Miami for 2025.
Now, when you’re creating your detailed budget, you need to think about all the individual pieces that come together to create your finished kitchen. Kitchen cabinets alone can run anywhere from $2,000 to $10,600, depending on whether you go with stock cabinets or splurge on custom ones. Countertops typically cost between $1,900 and $4,400 for materials and installation.
Appliances deserve their own line item because they can really add up. You might spend as little as $350 for a basic appliance or as much as $8,000 for a high-end smart refrigerator. A new sink installation runs $220 to $650, while a kitchen faucet costs $160 to $370. Don’t forget about the garbage disposal ($100 to $1,500), a tile backsplash ($500 to $1,700), and tile flooring ($400 to $6,500).
Even the smaller details matter. Light fixtures can range from $160 to $950, and plumbing fixtures might cost $330 to $1,800. When you add it all up, you can see how quickly the numbers climb.
Here’s something many homeowners forget: you also need to factor in the costs associated with your kitchen renovation loan itself. Interest payments and any origination fees should be part of your overall budget calculation. Understanding the true total cost helps you borrow the right amount without any surprises down the road.
And please, please set aside a contingency fund. We recommend adding at least 10% of your total project budget for unexpected expenses. Old homes, especially here in Dania Beach, love to surprise us once we start opening up walls. Maybe there’s outdated wiring that needs updating, or we find water damage that needs repair. Having that cushion keeps your project moving forward smoothly. For more ways to stretch your renovation dollars, read our Budget-Friendly Tips for Kitchen Remodeling in Miami.
Common Kitchen Projects You Can Finance
Here’s the great news: a kitchen renovation loan isn’t just for those massive, tear-down-to-the-studs renovations. You can finance almost any kitchen improvement project, whether it’s a single upgrade or a complete change.
Many of our clients use financing to replace or refinish their cabinets. Sometimes you want brand-new custom cabinetry, and other times a professional refinishing job can completely change the look of your existing cabinets for a fraction of the cost.
Countertop upgrades are another popular financed project. Switching from laminate to granite, quartz, or another premium surface instantly lifts your kitchen’s appearance and functionality. We’ve put together a guide on Elevate Your Kitchen with My Top Premium Countertop Choices that might help you decide.
Thinking about new appliances? Financing makes it easier to upgrade to energy-efficient models that’ll save you money on utility bills over time. You might even qualify for rebates on certain ENERGY STAR certified appliances, further stretching your budget. Smart appliances are becoming incredibly popular too. Learn more about Embracing Smart Appliances in Your Miami Kitchen Design.
Flooring upgrades can completely transform how your kitchen feels. Whether you’re drawn to durable tile, warm hardwood, or modern luxury vinyl, new flooring sets the foundation for your entire design.
A kitchen island adds so much value to your space. It creates extra workspace for meal prep, provides additional storage, and becomes a natural gathering spot for family and friends. We wrote all about why Kitchen Islands as Stylish Functionality Essentials.
Don’t overlook the impact of updated lighting fixtures. The right lighting changes not just how your kitchen looks but how it functions. Plumbing work, whether you’re relocating a sink, installing a stylish new faucet, or adding a pot filler, often requires professional expertise. A beautiful backsplash adds personality while protecting your walls. And even minor layout modifications can dramatically improve how your kitchen flows and how efficiently you can work in it.
The bottom line? Whatever kitchen improvement you’re dreaming about, financing can help make it happen without emptying your savings account all at once.
Open uping Your Funds: A Guide to Kitchen Renovation Loan Options
Now that we have a good idea of what your dream kitchen might cost, let’s talk about how to actually pay for it. You might be thinking, “I’ll just save up and pay cash,” and while that’s admirable, it’s not always the smartest move – or even realistic for most families.
Here’s the thing: using a kitchen renovation loan lets you keep your savings intact for emergencies (because life has a way of throwing curveballs). It also means you’re not liquidating investments or draining accounts you’ve worked hard to build. And honestly? With today’s competitive rates, financing often makes more financial sense than putting everything on a high-interest credit card.
Plus, loans give you predictable monthly payments, which makes budgeting so much easier. You know exactly what you owe each month, and you can plan accordingly.
There are several financing paths we can explore together, and each has its own personality. Personal loans are unsecured, meaning you don’t need to put up your home as collateral. They’re fast, flexible, and perfect if you don’t have significant home equity or prefer not to risk your property. You can typically borrow between $5,000 and $100,000, with interest rates ranging from 7.99% to 39.9% APR depending on your credit score and lender.
Home equity loans, on the other hand, are secured by your home’s equity. Because they’re backed by your property, they usually come with lower interest rates than personal loans. You receive a lump sum upfront and repay it over a fixed term, often 5 to 30 years. This option works beautifully if you’ve built up substantial equity and want to take advantage of those lower rates.
Then there’s the Home Equity Line of Credit, or HELOC, which works more like a credit card than a traditional loan. You get approved for a credit line, and you can borrow what you need, when you need it, up to your limit. This is ideal if you’re planning ongoing renovations or aren’t sure of the exact final cost. HELOCs typically have variable interest rates, so your payment can fluctuate over time.
And don’t overlook contractor financing. Many renovation companies (including us at Palmetto Kitchen & Bath Center) offer financing options that can include promotional periods with 0% APR for 6 to 12 months. These programs can be incredibly helpful, especially if you can pay off the balance before the promotional period ends. You can explore more about these options through our Kitchen Remodel Financing Options page.
Interest rates vary widely based on the loan type and your personal financial profile. Personal loans might run anywhere from 7.99% to 39.9% APR, while home equity products often start in the 6% to 9% range for well-qualified borrowers. Your credit score, income, and debt-to-income ratio all play starring roles in determining what rate you’ll qualify for.
Repayment terms are equally diverse. Personal loans typically span 2 to 12 years, while home equity loans and HELOCs can stretch out to 15 or even 30 years. Longer terms mean lower monthly payments, but you’ll pay more interest over the life of the loan. It’s all about finding that sweet spot that fits your monthly budget and long-term financial goals.
One trend we’ve noticed is the rise of online lenders. These digital-first companies often provide faster approval times, streamlined applications, and competitive rates. You can apply from your couch in your pajamas (no judgment here!) and sometimes receive funding within 24 to 48 hours. Traditional banks and credit unions are still solid options, especially if you prefer face-to-face interactions and have an existing banking relationship.
What is a kitchen renovation loan and how does it work?
At its core, a kitchen renovation loan is simply borrowed money earmarked for upgrading your kitchen. But the details matter, so let’s break this down.
Unsecured personal loans don’t require collateral. You apply, the lender reviews your credit and income, and if approved, you receive funds directly into your bank account. There’s no lien on your home, which means less risk for you – but potentially higher interest rates for the lender’s increased risk.
Secured loans, like home equity loans and HELOCs, use your home as collateral. This backing allows lenders to offer lower rates, but it also means your home is on the line if you can’t make payments. It’s a trade-off worth considering carefully.
Understanding fixed versus variable rates is crucial. Fixed-rate loans lock in your interest rate for the entire loan term, giving you consistent monthly payments. Variable-rate loans (common with HELOCs) fluctuate with market conditions. They might start lower, but they can also climb unexpectedly, affecting your budget.
Most kitchen renovation loans provide a lump-sum distribution – you get all the money upfront. This works perfectly for projects with defined costs and timelines. Some options, like HELOCs, let you draw funds as needed, which adds flexibility if your project scope evolves.
How lenders determine your rate comes down to three main factors: your credit score (higher scores = lower rates), your income and employment stability, and your debt-to-income ratio (how much you owe compared to what you earn). Lenders want confidence you can handle the payments without stretching yourself too thin.
For more detailed information on financing your project, visit our comprehensive guide on Kitchen Remodel Financing Options.
Choosing the Right Loan for Your Project
Not all loans are created equal, and the “best” option really depends on your specific project and financial situation. Let’s figure out what makes sense for you.
Matching loan type to project scope is essential. Planning a quick cabinet refresh and countertop swap? A smaller personal loan or contractor financing with a promotional rate might be perfect. Tackling a complete gut renovation with structural changes? A home equity loan or HELOC with a larger borrowing limit and longer term probably makes more sense.
Think about whether this is a one-time project or ongoing renovations. If you’re planning to remodel your kitchen now and tackle the bathrooms next year, a HELOC’s revolving credit line could serve you better than multiple separate loans. But if this is a singular project with a clear beginning and end, a fixed personal loan or home equity loan provides structure and predictability.
We always recommend comparing offers from at least three different lenders. Rates, fees, and terms can vary significantly, and shopping around could save you thousands of dollars over the life of the loan. Don’t just look at the interest rate – consider origination fees, prepayment penalties, and the total cost of borrowing.
Keep an eye out for special promotions. Some lenders and contractors offer limited-time deals, especially during slower seasons. 0% APR offers can be game-changers if you’re confident you can pay off the balance during the promotional period. Just read the fine print – these deals often come with deferred interest, meaning if you don’t pay it all off in time, you could be hit with retroactive interest charges.
For more strategic advice on planning your renovation, check out our Smart Strategies for Successful Kitchen Remodeling in Miami.


