
Quick Answer: Your Kitchen Remodel Financing Options
Kitchen remodel financing helps homeowners achieve their dream kitchen without depleting their savings. If you’re facing outdated cabinets or poor functionality, understanding your financing options is the first step.
Here are the main ways to finance your kitchen renovation:
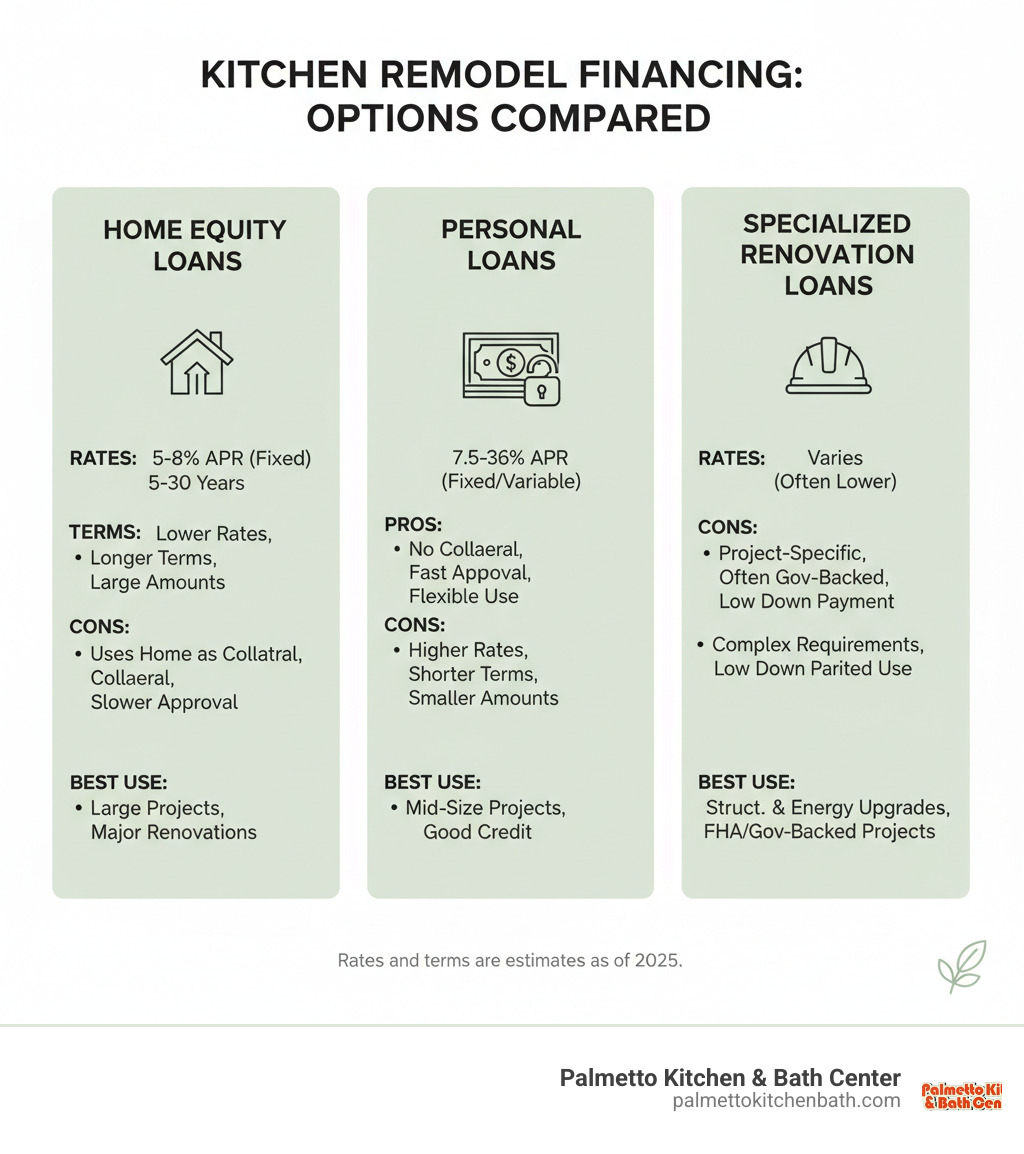
Secured Loans (Using Your Home)
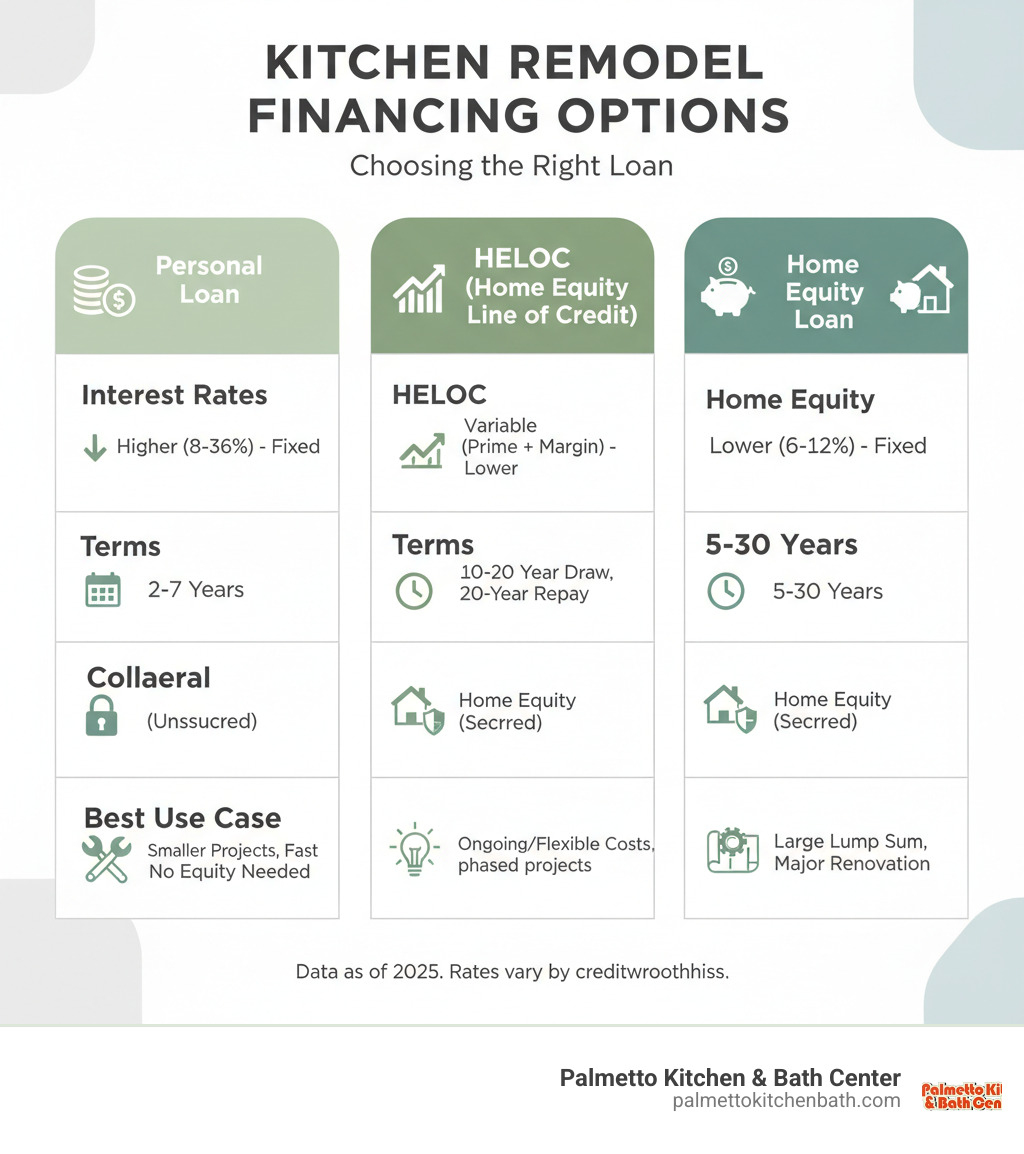
- Home Equity Loan – Fixed rate, lump sum, typically 5-8% APR
- HELOC – Flexible draw period, variable rate, 10-year access to funds
- Cash-Out Refinance – Replace mortgage with larger loan, rates vary
Unsecured Loans
- Personal Loans – No collateral needed, $1,000-$100,000, rates 7.5%-36%
- Credit Cards – Best for small projects only, highest rates
Specialized Programs
- FHA 203k – Government-backed, 580+ credit score, 3.5% down
- Fannie Mae HomeStyle – Up to 80% of future home value, 620+ credit score
The cost of a kitchen remodel typically ranges from $27,500 to $158,500, making financing a practical choice. A well-executed kitchen remodel can return 65-80% of its cost in added home value, with some renovations approaching a 90% return on investment.
Many homeowners worry about draining their savings for a renovation. But with secured loan rates as low as 5-8% and fast approvals for personal loans, financing can be a smarter choice than paying cash, allowing your savings to earn returns elsewhere.
The key is understanding which financing option fits your specific situation. Your credit score, home equity, project timeline, and budget all play a role in determining the best path forward.
Exploring Your Kitchen Remodel Financing Options
Finding the right kitchen remodel financing is about matching a solution to your specific needs. Whether you have substantial home equity, need fast funding, or are a recent buyer, there’s a path for you. Let’s explore how each option impacts your budget and financial health.

Secured Loans: Using Your Home’s Equity
If you have home equity, you can use it to secure a loan, which often comes with the lowest interest rates available—typically between 5-8%. The trade-off is that your home serves as collateral.
A Home Equity Loan provides a lump sum that you repay over a fixed period (5-30 years). With a fixed rate and payment, it’s predictable and ideal if you have a firm project cost.
A Home Equity Line of Credit (HELOC) is a flexible line of credit. During a draw period (often 10 years), you borrow as needed and may only pay interest. Afterward, you repay principal and interest. Most have variable rates, making them suitable for phased projects with uncertain costs. However, they require significant home equity, which recent buyers may lack. For more insights on how to tap into your home equity responsibly, check out this guide.
Cash-Out Refinance replaces your mortgage with a new, larger one, letting you cash out the difference for your remodel. It’s ideal if you can secure a lower interest rate than your current mortgage. You can typically borrow up to 80% of your home’s value but will pay 2-5% in closing costs.
Secured loans offer lower rates, longer terms, and potential tax benefits. However, the approval process takes 2-6 weeks, and your home is at risk if you default.
Unsecured Personal Loans for Kitchen Remodels
Unsecured personal loans offer a faster path to kitchen remodel financing without putting your property on the line. These loans are based on your creditworthiness and income, providing a lump sum of $1,000 to $100,000 that you repay in fixed installments over two to seven years.
A key advantage is speed; funds can be available the same day you apply. The process is simple, with no appraisals, and many loans have no prepayment penalties. Interest rates typically fall between 8% and 15% for borrowers with good credit but can be as high as 36%.
Since the average household savings often won’t cover a full remodel, personal loans allow you to preserve your emergency fund. While there are no tax benefits, you get fast approval without risking your home.
Specialized Renovation & Government-Backed Loans
For major overhauls or homeowners with little equity, specialized renovation loans are a great option. These loans base your borrowing power on your home’s after-remodel value.
FHA 203k Loans are government-backed loans that combine a home purchase or refinance with renovation costs into one mortgage. They have lower credit score (580+) and down payment (3.5%) requirements, making them accessible. However, you must use FHA-approved contractors and pay mortgage insurance.
Fannie Mae HomeStyle Loans are conventional loans that let you borrow up to 80% of the home’s after-renovation value, offering more flexibility with contractors and luxury upgrades. A credit score of 620+ is typically required, and inspections are part of the process.
Both options are ideal for homeowners with limited equity because you borrow against the value you’re creating. Pros include higher borrowing limits and terms designed for renovations. Cons include more paperwork, stricter requirements, and longer timelines. They are powerful but not quick solutions.
How to Choose the Best Loan for Your Project
Choosing the right kitchen remodel financing becomes clearer once you understand your project and financial situation. Let’s walk through the key factors to find a financing solution that fits your lifestyle.
Key Factors for Choosing Your Kitchen Remodel Financing
Before applying for loans, assess these factors to find a comfortable financing solution.
Your project scope will influence your loan choice. Minor updates (starting around $27,500) may suit a personal loan, while major renovations (up to $158,500 or more) often require a home equity or specialized loan.
Next, determine your total cost versus your loan amount. We offer free on-site consultations to establish a realistic budget. We always advise adding a 10-20% contingency fund to your contractor’s quote for unexpected issues. For a deeper dive into what different kitchen features actually cost, check out our guide on understanding kitchen remodeling costs in Miami.
Your timeline is also key. Personal loans offer fast funding (24-48 hours), while secured loans take 2-6 weeks for approval but provide lower interest rates and long-term savings.
Finally, consider your personal financial health. Your credit score and debt directly impact your approval and interest rate. A high score might secure an 8% rate on a personal loan, while a lower score could mean 20% or more. Check your score before applying to set expectations and make improvements if necessary.
Comparing Loan Rates, Fees, and Repayment Terms
Dive into the numbers to separate the good deals from the not-so-great ones.
Fixed-rate loans offer predictable monthly payments, while variable-rate loans (like most HELOCs) can fluctuate with the market. For budget stability, a fixed rate is often preferred.
Always compare the APR (Annual Percentage Rate), not just the interest rate. The APR reflects the true cost of the loan, including all fees.
Be aware of origination fees and closing costs. A cash-out refinance can have closing costs of 2-5% of the loan amount. Personal loans often have no upfront fees, making them appealing for smaller projects despite higher rates.
Check for prepayment penalties, which are fees for paying off your loan early. Many personal loans don’t have them, offering greater flexibility.
Choosing between short-term versus long-term loans involves balancing monthly cash flow against total interest paid. A shorter-term loan means higher monthly payments but less total interest. A longer-term loan lowers your monthly payment but costs more in interest over time. Find a balance that fits your budget.
The Application Process: From Pre-Qualification to Funding
Once you’ve chosen your kitchen remodel financing, the application process can be stress-free with proper preparation. Knowing what to expect makes it flow smoothly, just like following a recipe.
Preparing for Your Kitchen Remodel Financing Application
The secret to a painless application is organization. Here’s how to prepare.
First, establish a clear budget. Lenders need to see a realistic cost estimate. At Palmetto Kitchen & Bath Center, we offer free design consultations to help you develop one, showing lenders you have a solid plan.
Next, get contractor quotes. Detailed estimates show lenders you’re organized. These are required for specialized loans like FHA 203k or Fannie Mae HomeStyle and demonstrate a solid plan for any loan type.
Check your credit score before applying. It directly impacts your approval and interest rate. You can check your credit report for free at AnnualCreditReport.com to check for errors and see where you stand, giving you time to make improvements if needed.
Finally, gather your documents to speed up the process. This typically includes proof of income (W-2s, pay stubs), bank statements, and ID. For secured loans, you’ll also need property documents like mortgage statements.
Applying for a Loan and Receiving Your Funds
With your documents ready, the application is straightforward.
Start with pre-qualification. It uses a soft credit check that doesn’t affect your score and allows you to compare rates from multiple lenders without commitment.
Once you choose an offer, you’ll complete a formal application. This involves a hard credit check, which causes a small, temporary dip in your score. You’ll submit your documents for verification.
After a review, you’ll receive loan approval, detailing your approved amount and rate.
The funding timeline varies by loan type. Personal loans are fast, often funding within 24-48 hours. Secured loans take longer (2-6 weeks) due to appraisals and other steps. Specialized renovation loans can take even more time because of extra inspections.
Understand your funding timeline to coordinate with your contractor and avoid delays. At Palmetto Kitchen & Bath Center, we help time our work to match your financing availability for a smooth project flow.
Frequently Asked Questions about Kitchen Remodel Loans
We talk with homeowners daily about kitchen remodel financing. Here are answers to the three most common questions.
Are there tax benefits with kitchen remodel loans?
The answer depends on your financing type. If you use a secured loan (home equity loan, HELOC, cash-out refinance), the interest you pay might be tax-deductible. The IRS may allow you to deduct interest if the funds are used to “buy, build, or substantially improve” your home, which a kitchen remodel usually qualifies for. This can be a substantial benefit.
Interest on unsecured personal loans is generally not tax-deductible.
We are renovation experts, not tax advisors. Tax laws are complex, so we strongly recommend consulting a tax professional to understand what deductions you may qualify for based on your personal financial situation.
Can I finance the entire cost of my project?
Yes, many clients finance 100% of their kitchen remodel, including all labor, materials, appliances, and fixtures. You don’t need a large amount of savings to get started.
However, it’s wise to budget an extra 10-20% for a contingency fund. Surprises like outdated wiring or plumbing are common once walls are opened, and this buffer prevents project delays.
At Palmetto Kitchen & Bath Center, we provide detailed estimates during our free consultations to help you plan accurately. If you’d like to get a precise understanding of what your entire project might cost, we’re happy to provide an estimate.
How does financing impact my credit score?
Understanding the credit impact helps you make better financing decisions.
When you get pre-qualified, lenders use a soft credit check, which does not affect your credit score. This allows you to shop for rates worry-free.
A formal loan application results in a hard credit check, causing a small, temporary dip in your score. If you apply for multiple loans in a short period (14-45 days), credit bureaus often treat them as a single inquiry.
Most importantly, your payment history is the biggest factor in your credit score (35% of your FICO score). Making on-time payments is the best way to maintain and build your credit. Research shows that your track record of paying back loans consistently is a significant factor in your financial health.
A responsibly managed kitchen remodel loan can actually improve your credit score over time. Each on-time payment builds a positive history, showing lenders you are a reliable borrower.
Conclusion: Start Building Your Dream Kitchen Today
We hope this kitchen remodel financing guide has left you feeling empowered. The variety of financing options—from home equity and personal loans to specialized programs—means there’s a solution for every project, big or small.
With the right loan, you can preserve your savings, start your project sooner, and potentially gain tax benefits. While a kitchen remodel costs between $27,500 and $158,500, it’s an investment in your home’s value, with returns of 65-80% or more. More importantly, it’s an investment in your family’s daily comfort and enjoyment—returns that numbers can’t capture.
At Palmetto Kitchen & Bath Center, we partner with homeowners in Dania Beach and throughout South Florida to bring their visions to life. We offer custom renovations, guaranteed workmanship, and free, no-pressure on-site consultations.
We know financing is the bridge between dreaming and doing. We work with financing providers to offer flexible options for every situation, whether you’re a new homeowner or have lived in your home for years.
Your dream kitchen is a realistic goal achieved through smart financing. The first step is to check your credit, get a realistic project estimate, and explore the loan option that best fits your needs.
Don’t let another year go by in a kitchen that doesn’t work for you. The time to start is now, and we’re here to help make it happen. Start planning your Miami kitchen remodel with us today!


