
Why Bathroom Renovation Financing Matters for Your Dream Project
Bathroom renovation financing allows homeowners to spread the cost of their remodel over time, making upgrades affordable without depleting savings. Here’s what you need to know:
Quick Overview of Bathroom Renovation Financing Options:
- Home Equity Loan – Fixed-rate loan using your home as collateral (3-12% APR, 5-30 year terms)
- HELOC – Flexible credit line secured by home equity (similar rates, revolving access)
- Personal Loan – No collateral needed, faster approval (5-35% APR, 1-7 year terms)
- Contractor Financing – Direct financing through your remodeler (often 0% promotional periods)
- Credit Cards – Best for small projects under a few thousand dollars
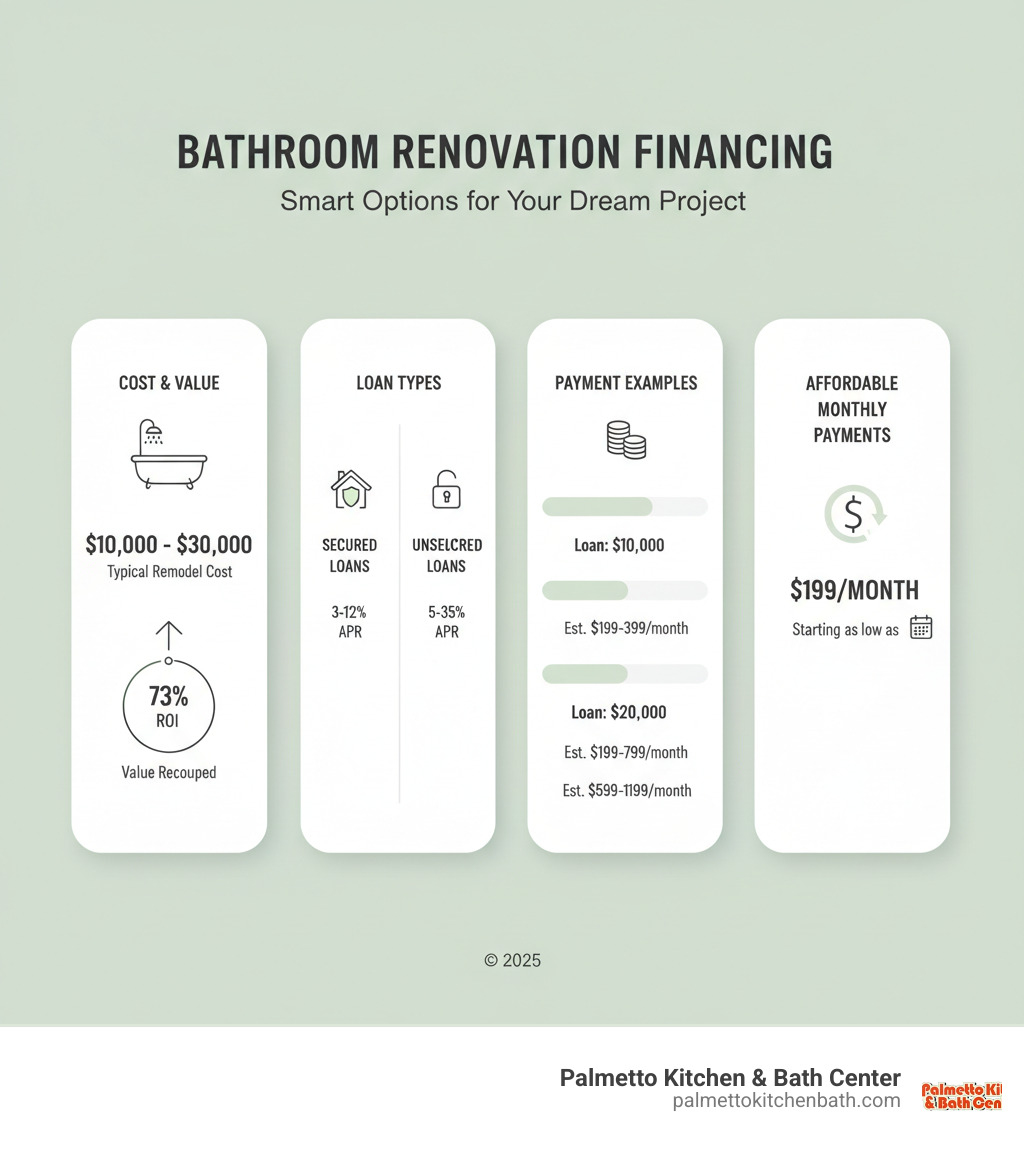
Hesitating over the cost of a bathroom remodel? You’re not alone. With the average project costing between $6,000 and $30,000, it’s a significant investment. That’s why nearly 70% of homeowners choose to finance their bathroom renovations.
Financing lets you enjoy your upgraded bathroom now while preserving your savings and investments. Plus, with homeowners recouping about 73% of their remodel costs at resale, according to The Journal of Light Construction, it’s a sound investment. The key is finding the right financing option, whether it’s a home equity loan for lower rates, a personal loan for speed, or another strategic choice that fits your financial goals.
First, How Much Does a Bathroom Remodel Cost?
Before choosing a bathroom renovation financing option, you need a budget. The national average cost for a bathroom remodel is between $6,622 and $16,771, but this varies widely.
A guest bath refresh might be $6,000 to $15,000, while a primary bathroom remodel could run $10,000 to $30,000. Mid-range projects average around $27,000, and upscale renovations can exceed $67,000 or higher.
The main cost drivers are:
- Scope of work: A cosmetic refresh (new paint, fixtures) is much cheaper than a full gut renovation that moves plumbing.
- Material choices: Stock items keep costs down, while custom cabinetry and high-end tile increase the budget.
- Labor costs: Accounting for 20% to 60% of the total, professional labor is a crucial investment in quality.
The good news is the return. According to The Journal of Light Construction report, bathroom remodels can deliver a 73% return on investment (ROI). Other estimates place ROI between 56% and 64%. More importantly, the National Association of Realtors notes that 35% of remodels directly improve homeowners’ quality of life.
For deeper insights into what influences these costs, check out our guide on Trustworthy Insights into Bathroom Renovation Cost Estimates. Understanding the numbers helps you make smart decisions about financing your project.
Your Guide to Bathroom Renovation Financing Options
Understanding bathroom renovation financing is simpler than it seems. Options fall into two main categories: Secured loans use your home as collateral, offering lower interest rates. Unsecured loans don’t require collateral, providing faster approval but typically at a higher interest rate.
Here’s a quick comparison of your main options:
| Financing Option | Collateral Required? | Typical Interest Rate (APR) | Typical Repayment Period | Pros | Cons |
|---|---|---|---|---|---|
| Home Equity Loan | Yes (Your Home) | 3-12% | 5-30 years | Fixed payments, generally lower rates, lump sum, interest may be tax-deductible | Home is collateral, closing costs, longer process |
| HELOC | Yes (Your Home) | Variable (similar to HEL) | 5-30 years | Flexible access to funds, interest-only payments during draw period, interest may be tax-deductible | Variable rates, home is collateral, temptation to overspend |
| Personal Loan | No | 5-35% | 1-7 years | Fast approval, no home equity needed, fixed payments, flexible use of funds | Generally higher interest rates, shorter terms, lower loan amounts |
| Credit Card | No | 15-30%+ | Revolving | Convenience, rewards (for small purchases), quick access (for small amounts) | Very high interest rates, risk of debt spiral, lower credit limits, can hurt credit score if not paid off quickly |
| Contractor Financing | Varies (often unsecured) | Varies (promotional 0% often) | Varies | Convenience, promotional rates (0% APR), custom to project, often fast | Potentially higher rates after promo, limited options, tied to specific contractor, may not cover entire project |
| Cash-Out Refinancing | Yes (Your Home) | Similar to new mortgage rate | 15-30 years | Potentially lower interest rate on entire mortgage, single payment | Resets mortgage term, closing costs, only makes sense if new rate is much lower than current |
Secured Loans: Using Your Home’s Equity
If you’ve built up equity in your home, secured loans can be your best friend, offering lower interest rates and longer repayment periods.
Home Equity Loans (HEL) work like a second mortgage. You get a lump sum based on your home’s equity and repay it with fixed monthly payments over 5 to 30 years. This offers predictable budgeting with rates from 3% to 12%. The interest may also be tax-deductible (consult a tax advisor). However, your home is collateral, meaning you risk foreclosure if you default. The process also involves closing costs and can take several weeks.
Home Equity Lines of Credit (HELOCs) provide a flexible line of credit you can draw from as needed, which is ideal for unexpected renovation costs. During the draw period (often 10 years), you may only pay interest on the amount used. Afterward, you repay principal and interest. The main drawbacks are variable interest rates, which can cause payments to fluctuate, and the temptation to overspend due to easy access to funds.
Cash-Out Refinancing replaces your current mortgage with a new, larger one, letting you use the cash difference for your renovation. It’s a good choice if you can secure a significantly lower interest rate than your current one, consolidating your debt into a single payment. However, it resets your mortgage term and involves substantial closing costs. It’s generally not recommended unless you’re significantly improving your mortgage terms.
Need help deciding between a home equity loan and a HELOC? Check out this helpful resource: Deciding between a Home Equity Loan vs a HELOC?
Unsecured Loans: No Collateral Required
If you haven’t built much equity or prefer not to use your home as collateral, unsecured loans are a great alternative, though they come with higher interest rates.
Personal Loans are fast and straightforward. You receive a lump sum and repay it with fixed monthly payments over 1 to 7 years. With no home equity required and funding possible in as little as one day, they’re a great option for newer homeowners. Rates (5-35%) are higher than secured loans, and loan amounts may be smaller, resulting in higher monthly payments due to shorter terms. For more details, visit More info about personal loans for remodels.
Credit Cards are best for small projects under a few thousand dollars. A 0% introductory APR card can be useful if you can pay off the balance before the promotional period ends (usually 12-18 months). However, standard interest rates are very high (15-30%+), and carrying a large balance can damage your credit score. Use them for minor purchases you can repay quickly, not for a full renovation.
Contractor-Offered Financing is an option we offer at Palmetto Kitchen & Bath Center, chosen by nearly 70% of our customers. We partner with financial institutions to streamline the process, often providing promotional rates like 0% interest for a set period (e.g., 12-60 months). This convenience is a major benefit. However, be aware that standard interest rates apply after the promotional period ends. Options are also limited to our lending partners and may not cover 100% of project costs if changes are made.
Want to learn more about why financing makes sense beyond just affordability? Our article on Benefits of Bathroom Remodeling covers how strategic financing can help you preserve cash and invest in your home’s value.
What Lenders Look For: Qualifying for Your Loan
When you apply for bathroom renovation financing, lenders assess several factors to ensure you can handle the payments. Understanding these can help you secure better terms.
- Credit score: A score of 700 or higher generally secures the best interest rates. Lower scores may still qualify but at a higher cost.
- Debt-to-income (DTI) ratio: Lenders prefer a DTI below 36-43%. This ratio is your total monthly debt payments divided by your gross monthly income.
- Income and employment stability: A steady job and consistent income are key. Self-employed applicants may need to provide more documentation.
- Home equity: For secured loans (HELs, HELOCs), lenders typically allow you to borrow up to 80-90% of your home’s value, minus your mortgage balance. More equity means more borrowing power.
- Loan amount: Smaller loan requests are generally easier to qualify for than larger ones, which require a stronger financial profile.
Getting your finances in order before applying can make the process much smoother. For more tips on preparing for your renovation, check out My Guide to Efficient Bathroom Renovation Planning.
The Application Process & Key Considerations
Once you’ve chosen a bathroom renovation financing option, the application process begins. Knowing the steps makes it more manageable.
Start with pre-qualification for a quick estimate of what you can borrow without impacting your credit score. For a firm offer, get pre-approved, which involves a hard credit check and results in a conditional loan offer.
After pre-approval, you’ll submit your full application and documents for underwriting, where the lender verifies your information. The final step is funding. Timelines vary from the same day for some personal loans to several weeks for home equity products.
A Step-by-Step Guide to Applying for Bathroom Renovation Financing
To ensure a smooth application, have your documents ready. Lenders typically require:
- A government-issued ID (driver’s license, passport).
- Proof of income (recent pay stubs, W-2s, tax returns; self-employed individuals may need more documentation).
- Recent bank statements.
It’s also wise to review your credit report for errors beforehand. Finally, provide detailed contractor estimates that outline the project scope and cost. Being organized can significantly speed up your approval time. For more tips on working with your remodeler, see 5 Things You Need to Discuss with Your Remodeler Before Bathroom Remodeling.
Special Considerations for Your Bathroom Renovation Financing
Keep these key considerations in mind:
- Florida Documentary Stamp Tax: In Florida, a state tax of about 0.35% is added to the principal of certain loans.
- Fixed vs. Variable Rates: Fixed rates offer predictable payments, while variable rates can change with the market, affecting your monthly cost.
- Prepayment Penalties: Ask if a loan has penalties for being paid off early. Many modern loans do not, but it’s important to confirm.
- Loan Term: A longer term means lower monthly payments but more total interest paid. A shorter term means higher payments but less interest overall.
- Contractor’s Role: Your contractor can be a key partner in financing. At Palmetto Kitchen & Bath Center, we provide the detailed estimates lenders require and work with financing partners to streamline the process for you.
To prepare for any surprises, read our guide on How I Prepare for Unexpected Bathroom Renovation Costs.
Frequently Asked Questions about Bathroom Remodel Loans
Here are answers to the most common questions we hear about bathroom renovation financing.
Is it better to finance a bathroom remodel or pay with cash?
The best choice depends on your financial situation. Financing is often preferred because it:
- Preserves savings and keeps your emergency fund intact.
- Maintains liquidity for other investments or emergencies.
- Spreads the cost into manageable monthly payments.
- Allows you to take advantage of zero-interest offers, potentially earning more on your investments than you’re paying in interest.
- May enable a higher-quality project, increasing home value.
Paying with cash is simpler and avoids interest payments entirely. You have no monthly payments or applications. If you have sufficient cash beyond your emergency fund and investments, paying upfront is a great option. For most, however, strategic financing provides the best path to a dream bathroom without sacrificing financial security.
Can financing cover the entire cost of a bathroom remodel?
Yes, financing can often cover the entire cost of a remodel, but it depends on several factors:
- Loan limitations: Personal loans may cap at $100,000, while home equity loans can be larger depending on your equity.
- Creditworthiness: Your credit score, DTI, and income determine your approved loan amount.
- Contractor financing: These options may have specific limits and might not cover unexpected overages.
- Project scope: A large-scale, $60,000+ remodel may require home equity financing, while smaller projects are easily covered by personal loans.
Get a detailed contractor estimate first, then confirm with lenders if their products cover the full amount. Always budget a contingency fund (10-15%) for unexpected costs.
What credit score do I need for a bathroom remodel loan?
The required credit score for bathroom renovation financing varies by loan type and lender.
- Personal loans: A score of 670+ is generally needed for the best rates, though some lenders work with scores in the 600s at higher rates.
- Home equity loans and HELOCs: Lenders typically look for scores of 620-680 or higher. Substantial home equity can help if your score is borderline.
- Contractor-offered financing: These programs can be more flexible, sometimes working with scores of 600+.
Even if your score isn’t perfect, lenders also consider your income and overall financial health. The best way to know your options is to get pre-qualified with several lenders, which uses a soft credit check and won’t affect your score.
Conclusion: Choosing the Right Path to Your Dream Bathroom
Choosing the right bathroom renovation financing comes down to your personal financial situation and project goals. Whether you opt for a low-rate Home Equity Loan/HELOC, a fast Personal Loan, or convenient contractor-offered financing, there’s a solution that fits. The best option depends on your credit score, home equity, and comfort with different loan terms.
At Palmetto Kitchen & Bath Center, we’re more than just remodelers; we’re partners in making your dream bathroom a reality. As a full-service contractor in Dania Beach, FL, we provide expert design, quality craftsmanship, and financing options to streamline your project. We’ve helped nearly 70% of our clients finance their remodels and are ready to guide you through the process.
During a free on-site consultation, we can discuss your design vision and the financial path that works for you. Your dream bathroom is within reach, and we’re here to help every step of the way.
Start planning your Fort Lauderdale kitchen & bathroom remodeling project today, and let’s turn that vision into reality together. Your perfect bathroom (and the perfect way to pay for it) is waiting.


